Case-Shiller from 3 months into the future

Wednesday, March 31, 2010

March '10 price crash

As you may have heard, the Fed has recently ended its mortgage-backed security buying program. Furthermore, Bank of America is increasing the foreclosure rate of its properties, from 7,500 homes a month nationally, with the goal to increase that number to 45,000 homes per month by December of 2010. On top of that, there's evidence of increased strategic defaults, and the $8,000 first-time homebuyer credit is about to expire.

All these factors, combined, appear to have created a perfect storm in the housing market. Just in the last month alone, all San Diego sub-markets crashed 10+% across the board, and it looks like the decline will only accelerate from this point on.

Thursday, March 4, 2010

February '10

All tiers are up slightly:

Monday, February 1, 2010

January '10 HPI

I missed a couple of months, but, fortunately, there was nothing interesting going on in the mean time.


Saturday, November 7, 2009

October '09


Clairemont and Mira Mesa appear to have staged a strong recovery. Here's a different perspective - smoothed median prices of a few different mid-range neighborhoods over time, and one top-tier neighborhood thrown in for comparison:


If we take two properties, one in Mira Mesa and the other in Ramona, that were worth the same amount, say, 300k in early '02, assuming no structural changes, the one in Mira Mesa is now worth 400k and the one in Ramona is only worth 325k. Other similarly priced peripheral locales, such as Alpine and Fallbrook, have also been underperforming. One possible explanation is that strength of Clairemont and Mira Mesa is due to their proximity to Sorrento Valley / University City tech hub, which has been affected by the downturn to a lesser degree than most of the city.

Friday, October 9, 2009

Temecula update

Unlike San Diego, the overhang of delinquent inventory in Temecula is so heavy that the summer rally was only able to stabilize prices for a while:

Friday, October 2, 2009

According to my calculations, city average index is now up slightly year-over-year:

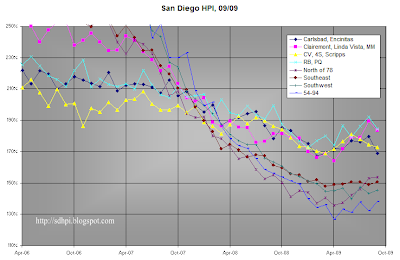


The official July Case-Shiller read came in at 150.99, in agreement with my expectations. The forecast is 154.5 for August, 158.0 for September, ~160 for October. At this point I don't expect any official reads indicating month-to-month declines before the end of the year (since the October number comes out around Christmas).

I have to caution against identifying this dynamics as genuine recovery, there's quite a bit of nonmarket stuff going on (the first-time-buyer tax credit, "shadow inventory", some degree of mortgage interest rate manipulation by the Fed), but the market appears to be robust and this uptrend has gone far beyond any seasonal fluctuations.